Egg Weekly: Post‑Surge Cooling, Correction Ahead(August 20)
Egg Weekly: Prices Surge Then Cool Down - Correction Signals Emerging
Domestic Egg Market Analysis
1.1 Egg Market Price Analysis
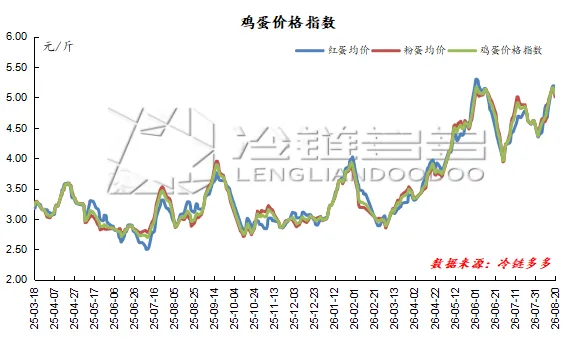
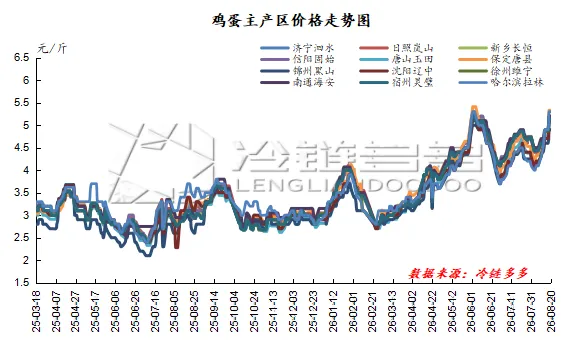
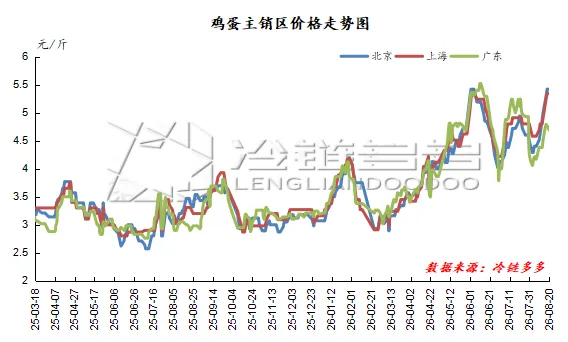
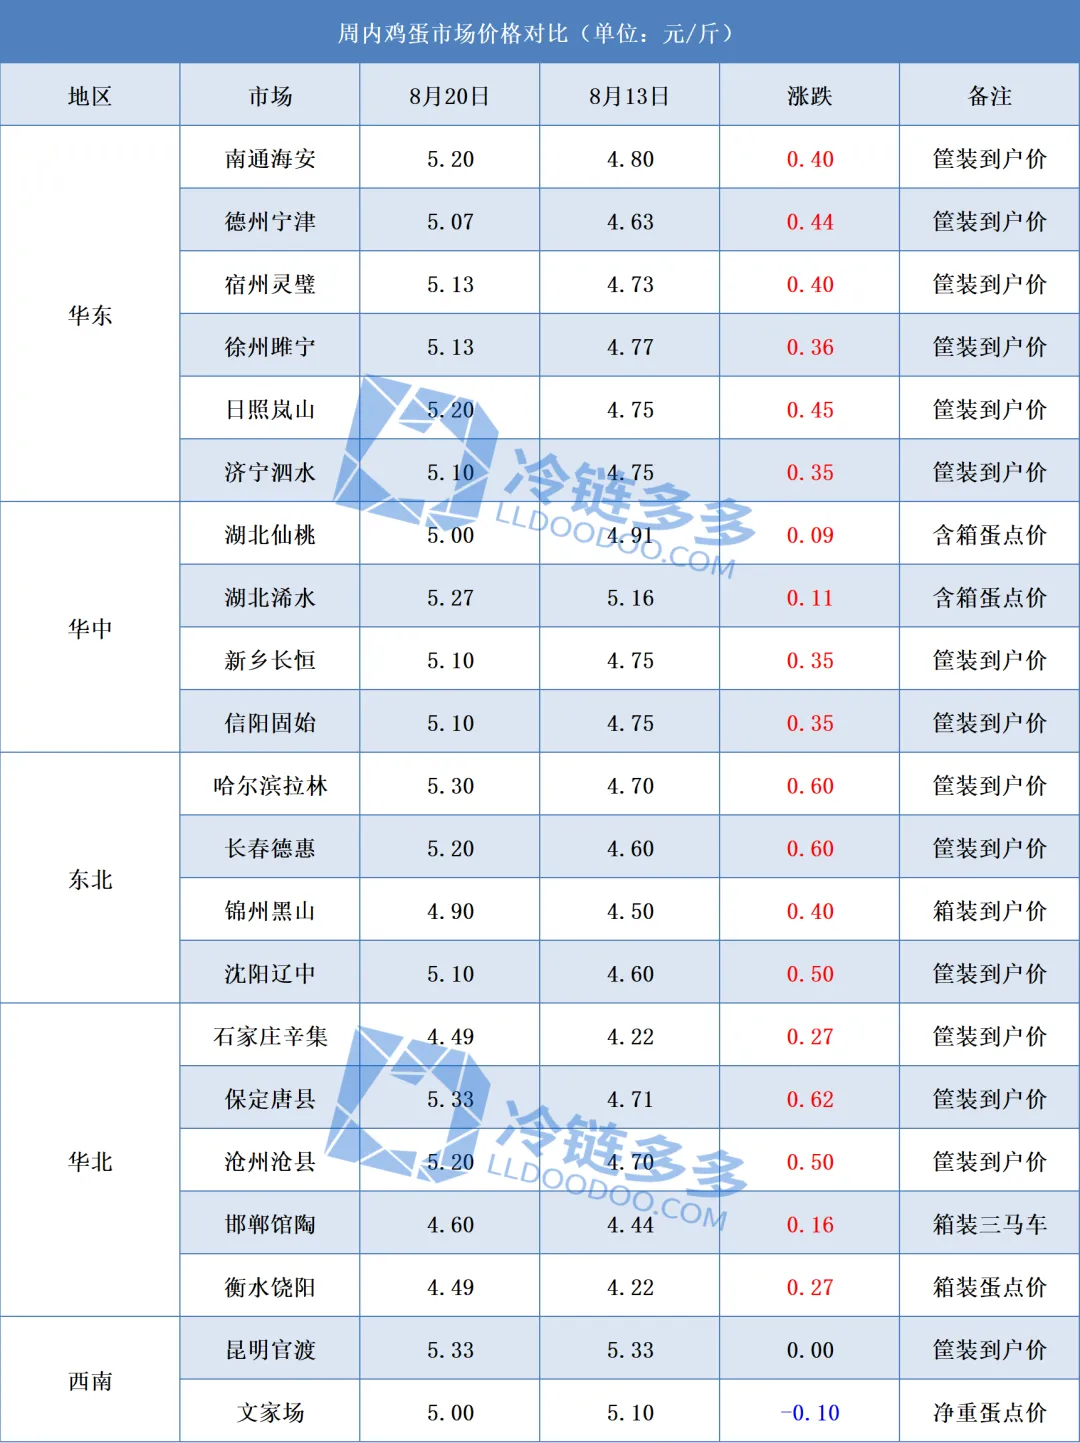
This week, the domestic egg market showed a trend of rising first then falling. As of Thursday this week, the average price of red eggs was 5.17 CNY/jin, up 0.39 CNY/jin from last week; the average price of pink eggs was 5.01 CNY/jin, up 0.10 CNY/jin from last week. The price spread between red and pink eggs continued to narrow, with a spread of 0.16 CNY/jin. This week, the egg market completed a shift from "strong surge" to "pressure at high levels." The Mid-Autumn Festival stocking window remains open, inventory across all segments has not yet formed significant pressure, and the probability of a sharp decline in the short term is low. However, signals such as weakening pink egg prices and increasingly cautious sentiment warrant attention. If demand release falls short of expectations, the market may face further correction pressure. In the short term, the market is likely to consolidate at high levels with volatility, requiring close attention to the drag effect of pink egg price trends on the overall market and changes in the pace of Mid-Autumn Festival stocking.
Production Areas:
As of Thursday this week, the average egg price in major production areas was 5.15 CNY/jin, up 0.36 CNY/jin from Thursday last week.
Distribution Areas:
As of Thursday this week, the average egg price in major distribution areas was 5.15 CNY/jin, up 0.46 CNY/jin from Thursday last week.
1.2 Egg Market Price Trend Chart
1.3 Regional Egg Market Price Comparison This Week
Laying Hen Inventory and Culling Analysis
2.1 Inventory Analysis
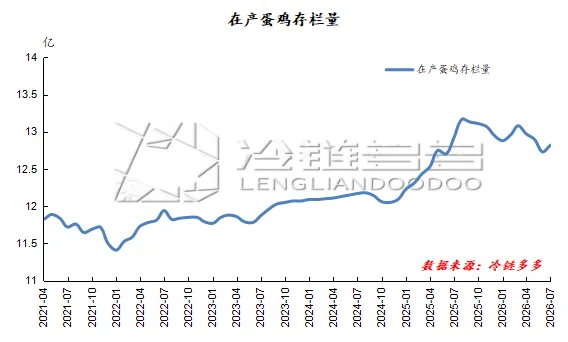
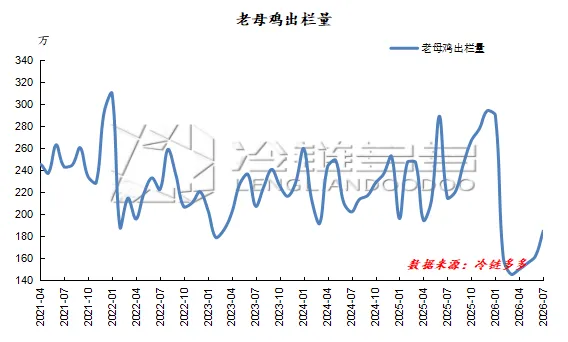
From the inventory structure perspective, the inventory of old laying hens remained at relatively high levels this week. The transmission effect of earlier restocking began to materialize in a concentrated manner. Restocking in April-May was at high levels, and the number of newly opened laying hens has increased significantly, leading to notable improvement on the supply side. The market supply-demand pattern is shifting from tight to loose. In actual performance, new production has clearly exceeded culling volumes, small-code egg supply continues to increase, and the price spread between large and small codes keeps narrowing, with structural differentiation characteristics weakening.
2.2 Culling Volume Analysis
This week, culling hen prices fell rapidly, culling volumes increased significantly, and the operating rate of slaughter enterprises improved somewhat. However, slaughter enterprises remain cautious about high-priced live hens, concerned about continued market weakness, and procurement increases have been limited. Although the farming side has a willingness to delay rearing, with a large inventory of hens awaiting culling, the actual culling pace still depends on the relative performance of egg prices and culling hen prices.
Egg Demand Analysis
This week, the Mid-Autumn Festival stocking window has opened. Food processing enterprises are mainly procuring in batches according to demand, without concentrated buying or large-scale inventory building. Trading operations are equally cautious, with a buy-and-sell strategy maintained throughout, inventory across all segments remaining low, and terminal delivery pace stable.
Egg Market Outlook
From the supply side:
The impact of high-temperature weather is weakening, and the egg market is entering the traditional peak consumption season. Farming profitability continues to improve, large-scale producers maintain normal restocking enthusiasm, and previously concentrated restocked laying hens are successively entering peak egg production. As a result, the trend of increasing supply in the longer term is becoming apparent.
From the demand side:
Although Mid-Autumn Festival stocking has begun, demand release has been relatively moderate. Food processing enterprises mostly procure in batches according to orders, without concentrated buying or large-scale inventory building. Traders similarly maintain a buy-and-sell strategy with limited willingness to stockpile. Inventory across all segments remains at low levels, delivery pace is stable, but peak-season demand is still in the process of gradual realization and has not yet reached its peak.
Comprehensive Outlook:
From the upside driver perspective, after consecutive price surges, the downstream absorption capacity has weakened, and the phenomenon of high prices suppressing demand has become increasingly apparent. In the short term, there is a lack of catalysts for another push higher. However, from the downside space perspective, inventory pressure across all segments is not significant, and Mid-Autumn Festival stocking demand is still being released, providing effective bottom support. Under the long-short tug-of-war, the probability of egg prices facing pressure at high levels with minor declines is gradually rising. The expected adjustment range is around 0.20 CNY/jin, with the average price in major production areas projected at 5.10-5.20 CNY/jin.